📊 Real Client. Real Numbers. Real Outcome.
You struggle with your finances even though you make $700K plus.
Meet a client of mine who faced this exact challenge.
The Starting Point
He was in his early 50s. Sales Director at a major US-listed tech company.
A high performer by any measure.
His income structure:
✔ $250K annual base salary
✔ $250K–$550K annual commissions — variable, performance-driven, never guaranteed
✔ $100K–$200K in RSUs vesting each year
On a good year, total comp north of $1M.
But the commission — nearly triple his base — wasn't always guaranteed.
That uncertainty made every long-term financial decision harder than it needed to be.
He had two goals:
🏡 Leave a legacy for his kids — specifically helping them get into the property market
💰 Retire early on $20K/month in passive income, with genuine financial peace of mind
What He Had When He Came to Us
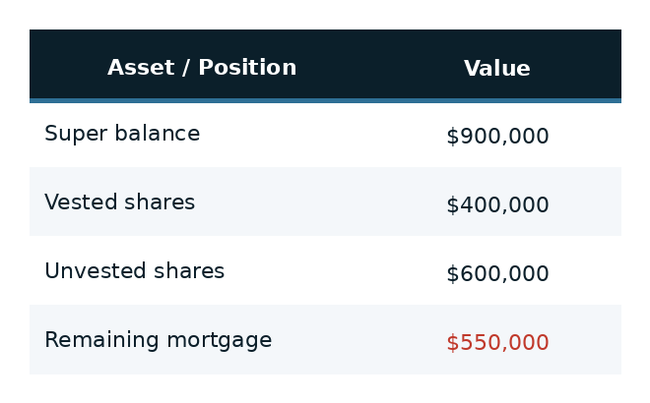
A solid foundation — but no coordinated plan. Every financial decision was made in isolation: a tax return here, a super balance growing untouched there, RSUs vesting and sitting in employer stock by default.
The result? High income. High effort. No compounding momentum.
His role was demanding. Passive income and early retirement weren't a luxury goal — they were an exit plan that needed a structure to make them real.
What We Did
1️⃣ Made the bonus work as a wealth accelerant, not a spending trigger
His commission — up to $550K in a strong year — was being absorbed by lifestyle and tax without a structured deployment plan. We treated each bonus as a scheduled event with a pre-set allocation:
- Priority 1: Tax provision set aside immediately at marginal rate
- Priority 2: Non-concessional super contribution up to the annual cap
- Priority 3: Mortgage reduction and investment portfolio top-up
- Priority 4: Lifestyle and discretionary spending from what remained
The framework meant he could live comfortably on his base salary alone — and the bonus became a genuine wealth-building event every year it came in.
2️⃣ RSU sell-down and diversification
He held $400K in vested shares — 100% in employer stock. We applied the 33% RSU Rule:
- Sold 67% of vested shares to reduce the mortgage further and improve serviceability
- Redirected proceeds into a diversified portfolio of global funds and Australian shares
- Retained a capped position in employer stock — deliberate, sized, not emotional
- Set up a quarterly sell-down cadence aligned to each vest date going forward
3️⃣ Released $850K in home equity for investment
With the mortgage at $550K and strong property equity, we structured a debt recycling arrangement:
- Released $850K from home equity via an investment line of credit
- Deployed into a diversified portfolio of funds and shares — fully tax-deductible loan interest
- Connected him with a buyer's agent who secured a growth-corridor property in Brisbane
- The investment loan converted non-deductible debt into a wealth-building engine
4️⃣ Super optimisation
With a $900K super balance and a target of $3.5M+ in pension phase, the strategy focused on:
- Non-concessional contributions from RSU proceeds and bonus — up to $120K this FY, rising to $130K next FY
- Investment mix shift to high-growth allocation given the runway to preservation age
- Spouse super contributions to equalise balances and reduce pension phase tax
5️⃣ Legacy and protection planning
Both goals — retirement and legacy for the kids — required structural work beyond investments:
- Updated personal protection plan in the most tax-efficient structure available
- Established a testamentary trust within the will — ensuring assets pass to children in a tax-effective, protected structure
- Modelled multiple scenarios: different housing expenditure levels, investment strategies, retirement dates, and the impact on both goals simultaneously
The Outcome
⏳ He can retire sooner than he thought.
📈 With more wealth.
🛡️ Less risk.
🎯 And a clear, written path to $20K/month in passive income.
No more ad-hoc decisions. No more vest-day anxiety. No more wondering where the money goes.
He now has a legacy plan for his kids, a coordinated investment strategy, and — for the first time in years — the confidence that his financial position actually matches his income.
"He told me he feels more in control and far less anxious about his financial future."
That's what an integrated RSU plan delivers. Not just more money — more certainty.